Walk into the back store of almost any established office in Accra or Kumasi and you will meet the graveyard: a corner stacked with dead monitors, a printer nobody has switched on in three years, two air-conditioners waiting for a repair that will never happen, and a desk with one missing leg. Everything in that corner is still, technically, on the asset register. It is still being depreciated on paper, still counted in the insurance schedule, and still quietly inflating the picture of what the organisation owns. The equipment stopped being useful long ago; the paperwork never caught up.
Disposal is the least glamorous part of asset management and the part most organisations get wrong. Done casually, it leaks money, invites theft and produces the awkward audit moment where an item on the books cannot be found because it was scrapped by someone who told nobody. Done properly, it recovers value, clears space, and closes the loop on an asset's life. The difference is a simple, repeatable routine — and it begins with treating retirement as a deliberate decision rather than an accident.
Retirement is a decision, not an accident
An asset should leave your register because someone decided it should, not because it silently rotted. The trigger is usually one of a few situations: the item is broken beyond economic repair, it is obsolete and no longer supported, it has been lost or stolen, or it is being replaced and the old unit has residual value worth recovering. Whatever the reason, the first discipline is to name it. A one-line justification — "repair quote exceeds replacement cost" or "no longer compatible with current systems" — turns a vague "it's old" into a defensible record.
Naming the trigger also protects you from the two failures that bracket every messy disposal. On one side is the asset that is written off far too early because someone simply found it inconvenient; on the other is the asset that limps along for years, costing more in patched-up repairs than a replacement would, because nobody was willing to make the call. A stated reason forces that judgement into the open where it can be checked. It also means that months later, when an auditor or a new manager asks why a perfectly good-looking cabinet was scrapped, the answer already exists in writing rather than in someone's fading memory.
Step one: prove the asset is genuinely beyond use
Before anything is written off, confirm the condition honestly. For equipment, that often means a short technician's report or a repair quotation. A generator that needs a part costing more than a working second-hand unit is a clear scrap case; a laptop with a swollen battery may just need a cheap fix and a few more years of service. The point is to avoid two opposite mistakes: throwing away assets that still have life, and keeping dead weight on the books because nobody wanted to make the call. This is far easier when your register already carries an accurate fixed asset register with acquisition dates and costs to weigh the repair against.
The honesty of this step is worth guarding, because it is exactly where quiet fraud creeps in. An item declared "beyond repair" by the same person who then takes it home for a token price is a pattern every auditor has seen. Insisting on an independent condition check — a technician who is not the eventual buyer, a photograph of the fault, a written quote from an outside workshop — keeps the decision clean. It costs almost nothing and removes any suggestion that the write-off was arranged to suit a person rather than the organisation, which is precisely the doubt that later turns a routine disposal into an investigation.
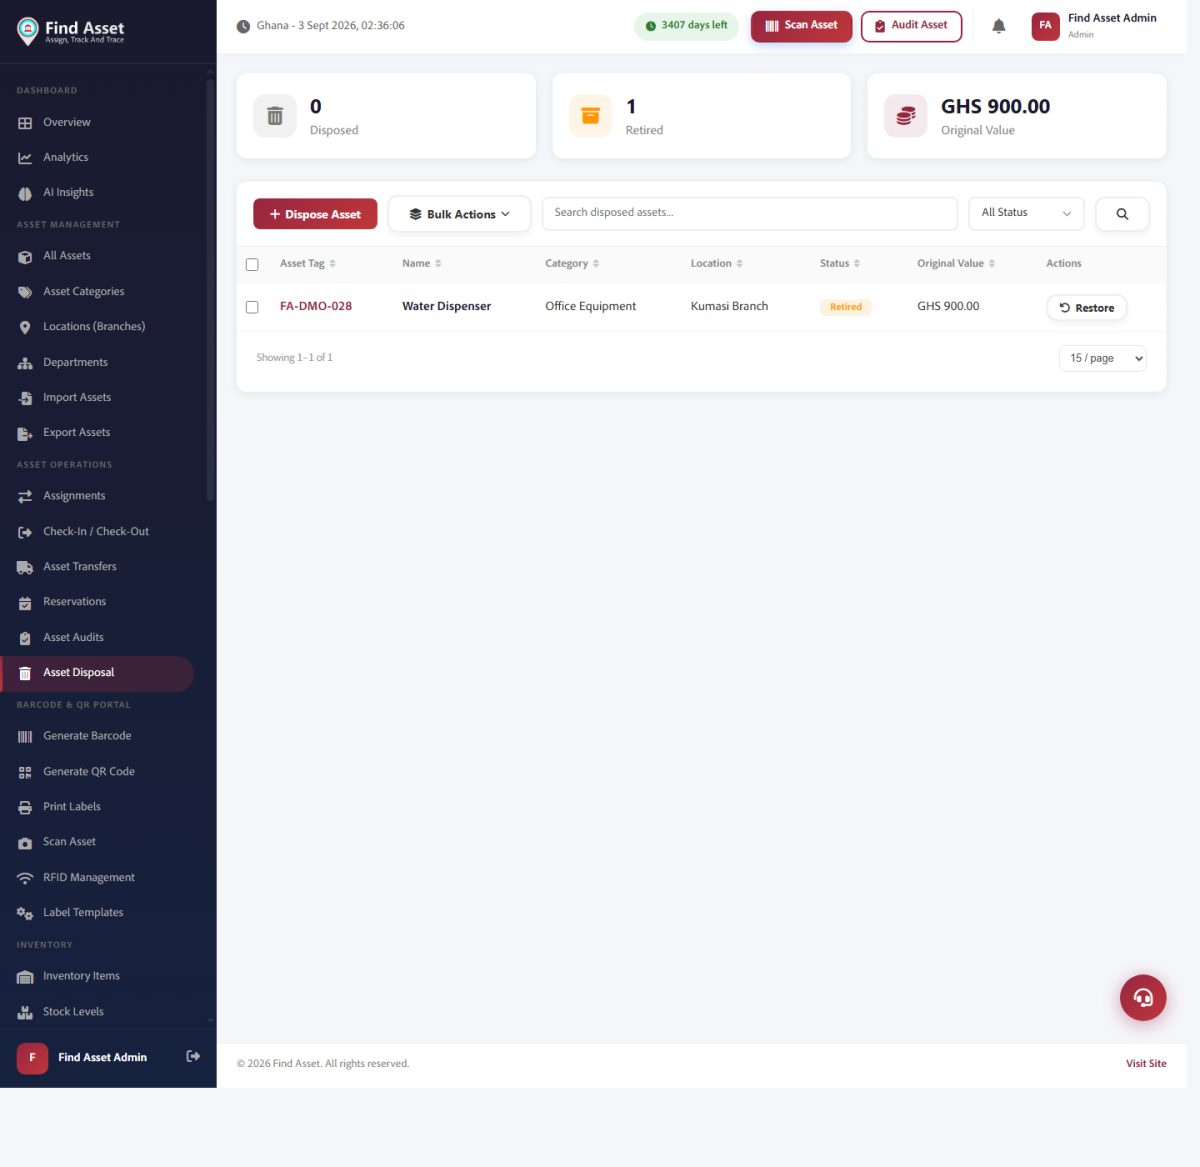
In Find Asset, retiring or disposing of an asset is a recorded event, not a deletion. The Asset Disposal screen above lists every item taken out of service with its tag, category, location, original value and a restore option, so a decision made today can still be traced — and reversed — months later.
Step two: get the write-off approved by the right people
Removing an asset from the register is a financial event, and it should carry the same seriousness as buying one. Someone with authority — a finance head, a management committee, or in the public sector a board of survey — should approve the disposal in writing. The approval need not be elaborate: the asset's identifier, its book value, the reason for disposal and the proposed method are enough. What matters is that the decision is made by a person entitled to make it, and that the approval is filed with the asset's record. This single step prevents the most common fraud in asset management: staff quietly disposing of items and pocketing the proceeds.
It is worth matching the level of sign-off to the value at stake, so the control does not become a bottleneck that people route around. A worn office chair should not need a committee, while a fleet vehicle or a bank of servers clearly should. Set a simple threshold — anything above a certain book value goes to a named approver, everything below can be signed off by a supervisor — and the process stays proportionate. When approval is quick and sensible for small items, staff actually follow it; when every biro requires three signatures, they stop asking altogether and the whole control quietly collapses.
Step three: choose the disposal route that recovers the most value
Not every retired asset is worthless. Before sending anything to the scrap heap, match the item to the route that returns the most — in money, in goodwill, or in responsible handling.
| Route | Best for | What to keep |
|---|---|---|
| Resale | Vehicles, furniture, working electronics | Open sale record or sealed bids |
| Trade-in | Like-for-like replacements | Supplier credit note |
| Donation | Usable items, community goodwill | Signed donation letter |
| Recycling | Electronic waste | Recycler's receipt |
| Scrap | No use, no resale value | Photo + weight/value note |
An open, documented sale protects you from accusations of favouritism, and matching the asset to the right route is where real money is saved or lost. A working laptop pushed straight to scrap because it was easier throws away resale value that could have offset the cost of its replacement; a batch of desks quietly sold to a staff member's relative for a nominal sum invites exactly the suspicion the routine is meant to prevent. Advertise resale items even briefly, invite a couple of sealed offers for anything of real value, and keep the record of who bid what. The small effort of running an open process almost always returns more than the private shortcut, and it buys something harder to price: the confidence that nobody skimmed the proceeds.
Step four: remove it from the register and keep the trail
Only after the item has physically left should you mark it disposed in your records — never before, or you create a window where an asset is "gone" on paper but still sitting in the building. A proper disposal record captures the date, the method, who approved it, any proceeds received, and where those proceeds went. Keep the supporting documents together: the approval, the sale receipt or donation letter, and a photograph if the item was scrapped.
The sequencing here is not pedantry; it closes the single most exploited gap in the whole process. If the register is updated first and the item leaves later, there is a period in which the equipment is officially untracked but physically present, and things that are untracked have a way of walking off. Tie the two events together — the de-registration and the physical handover happen on the same day, evidenced by the same paperwork — and that window never opens. When the dates on the record and the gate pass match, an auditor can follow the item from the balance sheet to the door without a single unexplained day in between.
A disposal record that survives an audit
- The asset's permanent identifier and its book value at disposal.
- The reason, in one honest line, and who approved it.
- The route taken and any proceeds — plus where the money went.
- Proof: a receipt, a donation letter, or a photo of the scrapped item.
- The date the item physically left, matching the date you de-registered it.
Do not forget the data on the device
One disposal risk sits outside the asset register entirely and is routinely ignored: the information left on the equipment. A retired laptop, phone, photocopier or server can carry years of confidential files, and photocopiers in particular quietly store images of everything they have ever scanned. Handing such a device to a buyer or scrap dealer without wiping it is a data breach waiting to happen. Build a simple rule into your routine: no device that ever stored data leaves the building until its storage has been securely erased or physically destroyed. Responsible handling of end-of-life electronics is also increasingly a legal and environmental expectation — the growing global e-waste problem is one every organisation now shares in.
The catch is that the risk hides in unexpected places, so a vague instruction to "wipe things" is not enough. Deleting files or a quick format leaves data fully recoverable with free tools, which means the standard has to be a proper wipe or the physical removal and destruction of the drive. Network printers, routers, and even some modern air-conditioners and access-control panels hold credentials or logs that a new owner should never see. Keep a short list of which asset categories require data handling before disposal, and make signing off on the wipe a mandatory field on the disposal record, so the step cannot be skipped in the rush to clear a store room.
Why the paperwork is really about trust
Auditors do not chase disposal records to be difficult. A missing asset with no disposal trail looks identical to a stolen asset, and they have no way to tell the two apart without your documentation. Every clean disposal record you keep is one fewer unexplained gap in the count, and one more reason for management, funders and auditors to trust your numbers.
That trust compounds well beyond the audit itself. Funders and boards read a clean disposal history as a sign that the whole organisation is run with discipline, because the way you handle the unglamorous end of an asset's life says more about your controls than the way you handle a purchase. A grant-maker deciding whether to fund new equipment is reassured by evidence that the last batch was tracked to its documented end rather than vanishing into a store. In that sense the disposal file is not an accounting formality at all; it is a small, repeated proof that what the organisation says it owns and what it actually holds are the same thing.
Bringing it together
Retirement is a decision, condition is proven, write-off is approved, value is recovered through the right route, data is wiped, and only then does the item leave the register — with a paper trail behind it. Handle the end of an asset's life with the same care you gave its purchase and the register stays honest from the first day to the last. If you would like that whole loop to live in one place instead of scattered files, you can start a free 14-day trial and give every asset a clean beginning and a documented end.
None of these steps is difficult on its own; the discipline is simply doing them in order, every time, even for the humble broken fan that nobody would miss. The organisations that struggle are not the ones that lack a policy but the ones that keep the policy for big-ticket items and wave everything else straight into the skip. Make the routine the default for every retirement, keep the record with the asset from purchase to disposal, and the back-store graveyard stops growing — because each item now has a documented way out rather than an indefinite stay on a register that no longer reflects the truth.